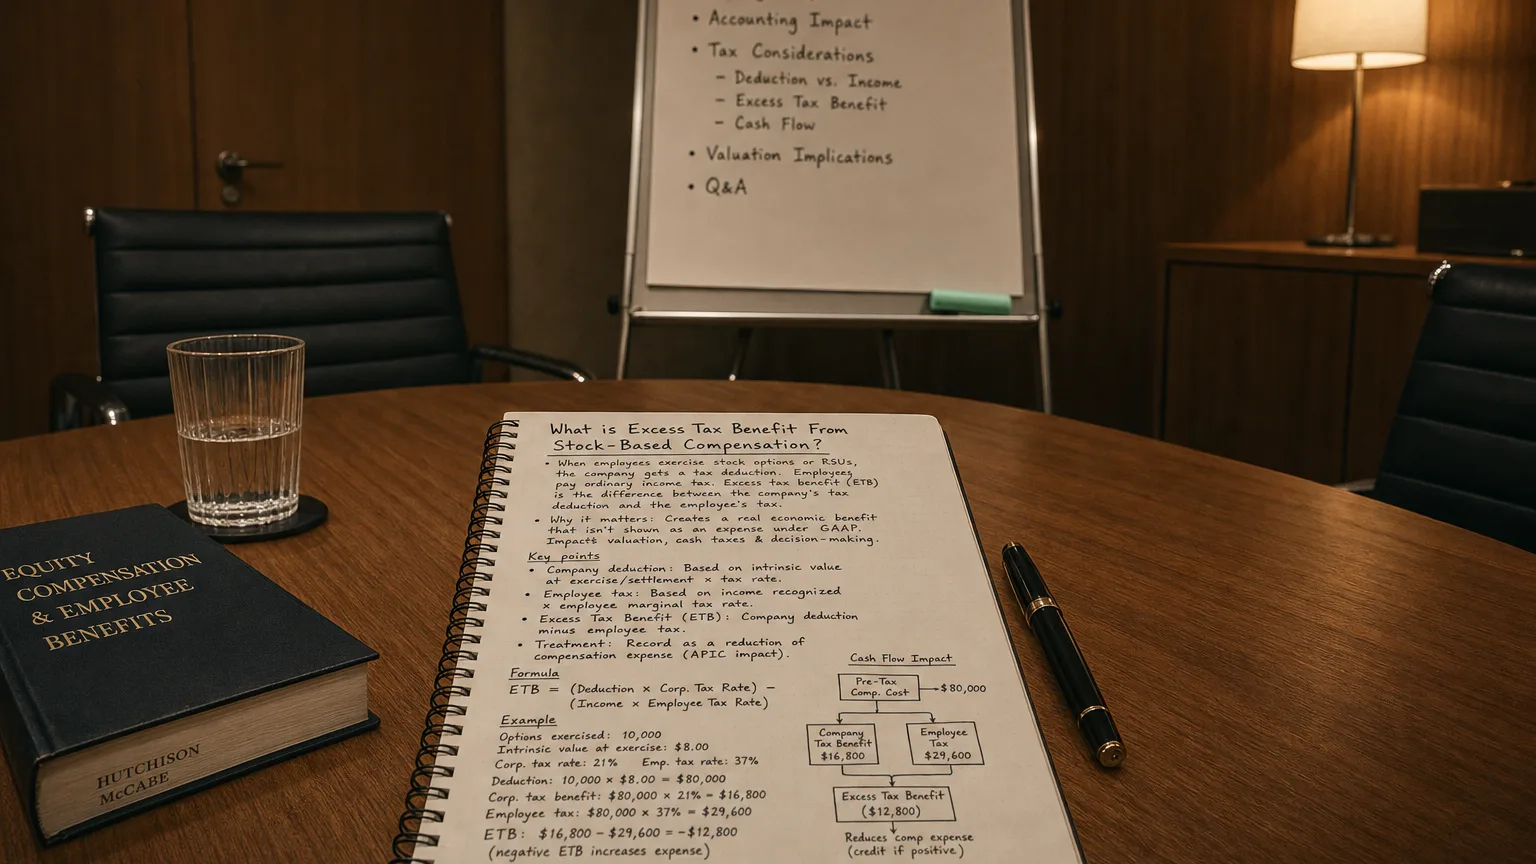
Excess Tax Benefit from Stock-Based Compensation is a financial concept covered in this article.
Pennies don't fall from heaven, they have to be earned here on earth.
Excess Tax Benefit from Stock-Based Compensation (also called Windfall Tax Benefit) was the additional tax deduction a company received when employees exercised stock options or vested in restricted stock/RSUs at a share price higher than the grant-date fair value used for book expense. This ‘excess’ created a cash tax saving that was reported as a financing cash inflow under old US GAAP rules (pre-2017).
How It Used to Work
Before 2017, companies expensed stock options at grant-date fair value (book expense). When exercised, the actual tax deduction was based on the intrinsic value (market price − strike).
If market price was higher, the extra deduction created a tax shield—the ‘excess tax benefit’.
This windfall cash saving went to financing cash flow and increased Additional Paid-In Capital.
A Clear Example
“Pennies don’t fall from heaven, they have to be earned here on earth.”
— Margaret Thatcher, Prime Minister of the United Kingdom Speech to the Conservative Party Conference (1979)
Employee gets options on 10,000 shares at $20 strike.
- Grant-date fair value: 100k book compensation expense over vesting
- Exercise when stock 30/share = $300k tax deduction
- Tax rate 30% → $90k actual tax saving
- Book expense deduction only 100k × 30%)
- Excess Tax Benefit: $60k
Pre-2017: +60k reduces income tax expense (operating).
The Big Change in 2017
ASU 2016-09 eliminated the APIC pool and excess benefit concept.
- All tax effects (excess or shortfall) now in income tax expense (operating)
- No more financing cash flow boost from exercises
- Shortfalls reduce tax expense (can create volatility)
- Simplified but more earnings swings
Tech companies with big option programs felt the biggest shift.
Where You’d See It (Old Statements)
In pre-2017 cash flow statements:
- Financing section: ‘Excess Tax Benefit from Stock-Based Compensation’
- Often material for growth/tech firms
- Boosted financing cash flow and OCF indirectly (via APIC)
Now: All in operating tax expense—no separate line.
Why It Mattered
- Non-cash boost to financing cash flow
- Increased APIC (equity)
- Made OCF look stronger indirectly
- Rewarded rising stock prices with tax savings
- Common in Silicon Valley option-heavy cultures
What to Look For in Old Data
- Size relative to stock comp expense (high = big stock price gains)
- Trend with option exercises
- Impact on financing cash flow quality
- Comparison pre/post-2017 (OCF volatility increased)
Pre-2017 excess benefits flattered financing cash—now gone.